

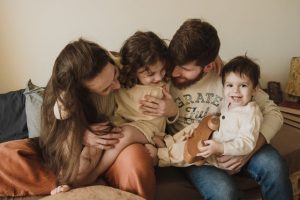
 When you are starting a career, raising young children, and settling into a home, estate planning rarely feels like a top priority. Most young adults treat wills and trusts as items for retirement, assuming wealth accumulation must happen before legal documents matter.
This assumption leaves young households vulnerable to unnecessary hardship. When you have a spouse, a partner, and/or dependent children relying on your income and physical presence, thoughtful planning becomes far more critical than it is later in life.
Older adults often leave behind financially independent adult children. Young parents, by contrast, leave behind dependents who require immediate physical care and years of financial support.
Intelligent estate planning for young families shields your loved ones from legal chaos, expensive court involvement, and emotional stress.
The Misconception of Waiting Until Retirement
If you ask most young parents in Washington County why they haven’t set up an estate plan, the answer usually involves time or money. You might feel you don’t own enough real estate, investments, or savings to justify formal legal documents.
Estate planning focuses on protection and control rather than sheer net worth. You create an estate plan to establish clear directions for healthcare emergencies, nominate guardians for your children, and manage how your family accesses funds if life takes an unexpected turn.
Delaying this process forces the state of Minnesota to step in and make those critical choices for you under default legal rules.
What Happens When You Pass Away Without a Plan
Dying without a valid estate plan is known as dying intestate. When this occurs, Minnesota statutes dictate who inherits your property and who steps in to handle your affairs.
Relying on state intestacy laws introduces significant complications for young parents:
- Unintended Asset Division: Minnesota law mandates the distribution of your assets according to fixed statutory formulas. The application of these default rules may lead to asset distributions that aren’t consistent with your actual wishes.
- Immediate Inheritance for Minors: Under state law, minor children cannot directly own significant property or accounts. If money passes to your young children, a judge appoints a legal conservator to manage those funds until the children turn 18.
- Lump-Sum Payouts at Age 18: When your children reach legal adulthood, court oversight ends. An 18-year-old child receives their entire inheritance outright with zero restrictions, creating a high risk of poor financial choices or lost funds.
- Public Court Proceedings: Without a trust or direct transfer mechanisms, your estate enters the probate court system. This process drags on for months, exposes your family’s finances to public record, and drains estate assets through court filing fees and legal costs.
Protecting Your Children: Guardianship Nominations
For most young parents, the most vital reason to establish an estate plan involves naming a legal guardian for minor children.
If both parents pass away unexpectedly, a judge must appoint a guardian to raise your children. Without a legal document outlining your preferences, the court makes this life-altering choice based on limited information.
Family members may compete in court for custody, leading to bitter battles, expensive litigation, and added trauma for your kids.
Through a basic will, you explicitly state who you trust to raise your children. You can also name alternate guardians if your first choice is unable to serve.
While the court technically gives final approval, your written nomination carries immense weight, giving you peace of mind that your children will remain in loving hands.
Financial Management Through a Revocable Living Trust
Naming a guardian solves the question of who provides daily care for your children, but it does not manage the money required to raise them. To protect your family’s financial future, a revocable living trust offers superior structure and security.
A living trust allows you to hold assets, including life insurance proceeds, real estate, and financial accounts, in a safe legal framework. You control everything as the trustee during your lifetime.
If you pass away or become incapacitated, your chosen successor trustee steps in to manage and distribute those funds according to your exact instructions.
A living trust delivers essential benefits for young households:
- Probate Avoidance: Assets held inside a trust transfer directly to your designated beneficiaries without going through the Minnesota probate court, saving thousands of dollars and avoiding months of unnecessary delay.
- Controlled Distributions: Instead of handing an 18-year-old a massive lump sum, your trust can hold funds and pay them out gradually over time. You might direct the trustee to cover college tuition, health expenses, and basic living costs, while releasing specific portions of the principal at ages 25, 30, or 35.
- Incapacity Protection: If an accident or severe illness leaves you unable to manage your financial obligations, your successor trustee steps in immediately to pay bills, cover the mortgage, and care for your family without requiring court intervention.
Essential Medical Directives for Young Adults
Estate planning extends beyond asset transfer after death; it also protects you during medical emergencies. Once you turn 18, your spouse or parents do not automatically maintain legal access to your medical records or the authority to make critical healthcare decisions for you.
Every young parent should have two foundational healthcare documents in place:
- Health Care Directive: This document combines a medical power of attorney and a living will. You name a trusted agent to make medical decisions on your behalf if you become incapacitated, while providing explicit guidelines regarding life-sustaining treatment and end-of-life care.
- Durable Financial Power of Attorney: You designate a trusted representative to handle your financial responsibilities, such as paying your mortgage, filing taxes, and managing bank accounts, if an emergency leaves you unable to act for yourself.
Without these documents, your family members must petition a court to appoint a legal guardian or conservator to make emergency choices, adding legal delays and steep court costs during a crisis.
Final Thoughts
Waiting for the “right time” to create an estate plan is risky business unless you have a crystal ball handy. There is no reason to roll the dice without a plan when you can easily work with an estate planning lawyer to protect your family, and you will sleep better at night when you do it.
Let’s Get Started!
To schedule a consultation at our Oakdale, MN estate planning office, send us a message or give us a call at 615-478-8999.
- Estate Planning for Young Families: Don’t Take Any Risks - October 15, 2026
- Medicaid Planning: What Can a Healthy Spouse Keep? - October 1, 2026
- Special Needs Planning: Key Considerations - September 15, 2026